
Nearly 45% of U.S. adults, and two-thirds of active investors, say financial stress or anxiety directly shapes how they invest, according to the Motley Fool's 2026 Financial Stress and Investing Survey. The effects include avoiding the stock market entirely, panic-selling during downturns, and obsessively checking portfolio balances.
Financial stress is widespread. Conducted on April 21, 2026, and included 2,000 American adults ages 18 and older, the survey found that 45% of respondents rate their current stress level a 4 or 5 on a 5-point scale, and 38% said they feel financially stressed often or every day. As The Motley Fool explains below, that persistent anxiety can affect investing decisions and can work against long-term financial interests.
Among respondents who currently invest, 41% said they feel stressed or anxious specifically about their investments sometimes, often, or every day. Among non-investors, more than a quarter cited reasons for staying out of stocks that connect to the emotional and mental burden of investing, although not having enough money to invest remains the primary barrier.
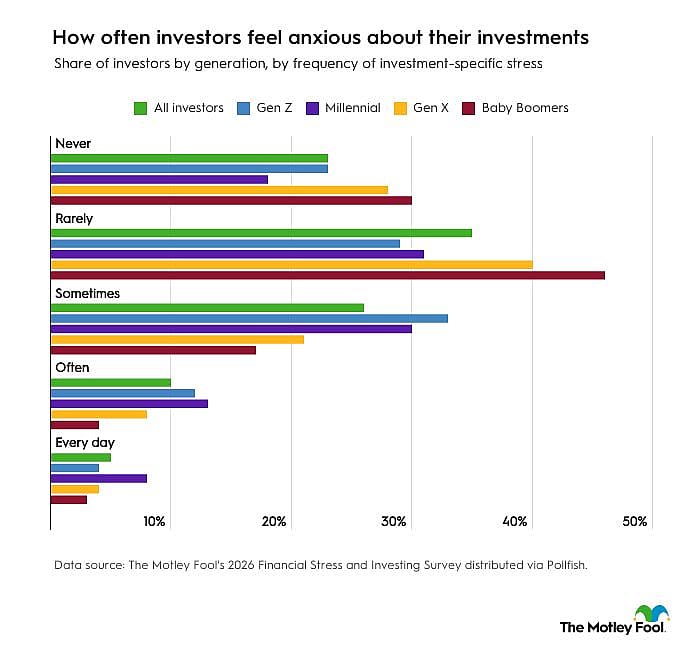
Emotional stress about investing specifically isn't the main reason people stay out of the market. Only 3% cite it directly. But it's part of a bigger pattern: Combined with distrust in the markets and simple confusion about how to start, psychological barriers keep more than a quarter of non-investors on the sidelines.
For those who can afford to invest but feel too intimidated to start, Tim Beyers, senior investment analyst and lead advisor at The Motley Fool, says the fix is smaller than people expect: "My favorite advice is to buy one share. That's it. Just one. The stock doesn't matter at that point. Just get used to creating the muscle memory of buying." From there, he recommends setting up a monthly dollar amount to invest, whether in index funds or a short list of five to ten stocks added to in equal amounts. "At the beginning," he says, "simplicity and repeatability are your best friends."
Among respondents who do invest, the data on stress is more pronounced. The survey asked investors directly whether financial stress or anxiety affects how they invest. Just 26% said it has no effect, 67% said it caused a behavior that can work against long-term investing goals, and the remaining 8% said it motivated them to invest more.
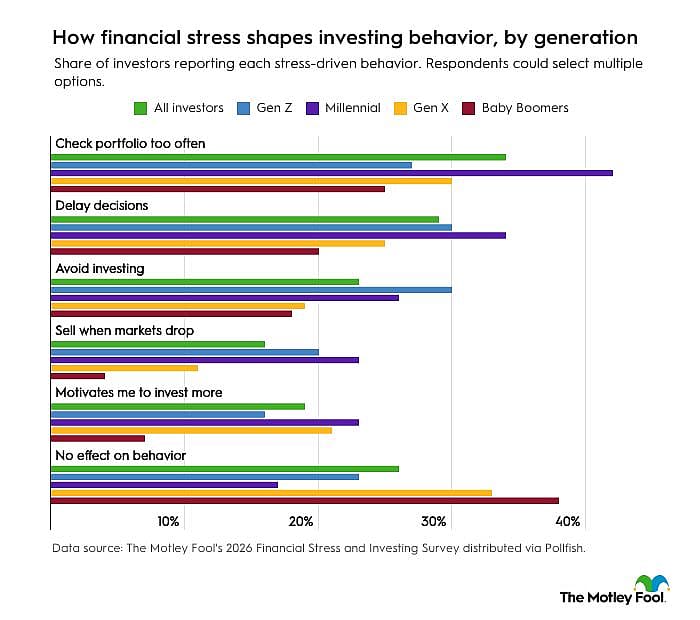
Younger investors, the group most likely to report frequent investment anxiety, are also the most likely to report stress-driven behavioral changes across every category the survey measured.
Thirty-eight percent of respondents reported making an investment decision driven primarily by emotion rather than by research or a plan.
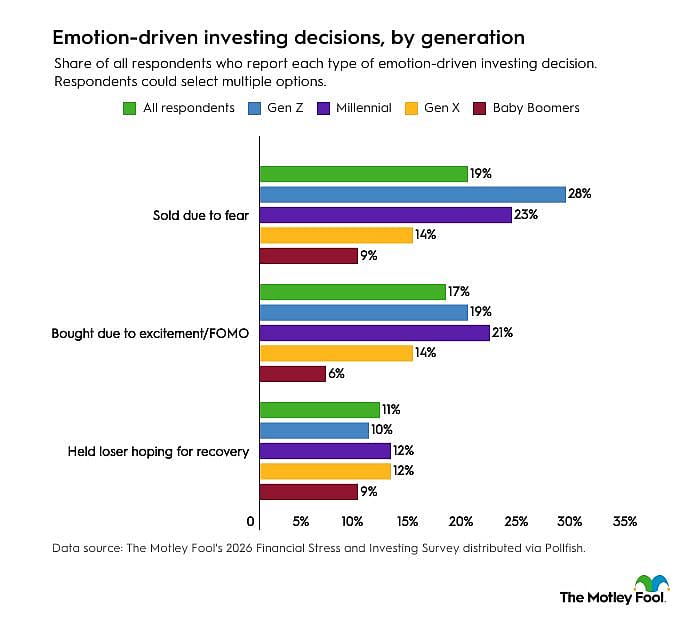
Emotion-driven decisions are significantly more common among younger respondents. Nearly half of Gen Z respondents (48%) and millennials (45%) reported at least one emotion-driven decision, compared to 32% of Gen X and 21% of boomers.
Beyers has felt that cost firsthand. "Too often, the cost of panic is selling a winner before it has a chance to become a winner," he says. "I've sold at least one stock that went on to return hundreds of times its original value and held others that, despite selling off by more than 75% at one point, have grown to occupy close to 20% of my total investable assets." Staying put isn't easy, he adds, but the edge individual investors have over algorithms and hedge funds is time: "When you recognize that time is the most important factor in compounding wealth, you'll become far less likely to interrupt it with a panic sale."
Beyers sees the survey's FOMO-buying and fear-selling figures, 17% and 19%, as two sides of the same coin. "Fear drives us away from the uncertain, i.e., volatile stocks that may not be popular yet, to the certainty of cash (in the case of selling) or a 'sure thing,' a winner you must own because everyone else does," he says. He makes a distinction between fear that protects you and fear that doesn't: "Some fear is healthy and keeps us safe from physical threats. Here we're talking about unjustified fear that leads us to portfolio-immolating action when holding fast would almost certainly be the better move."
Even investors who haven't made an emotion-driven decision feel the pull of market swings. Among respondents who follow the markets, 55% said market volatility has a major or some emotional impact on them.
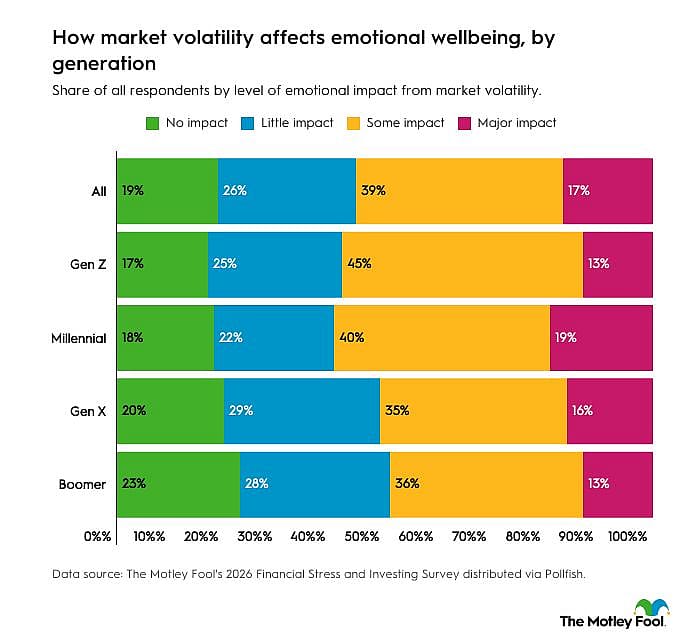
Market volatility is, by definition, temporary, but its emotional effects are not. Investors who respond to short-term swings with stress-driven behavior risk making permanent decisions in response to temporary conditions.
How Americans feel about their retirement savings tracks closely with where they actually stand. Among those who feel on track or ahead, 65% said their retirement situation affects their mental health positively. Among those who feel significantly behind, 51% said it negatively affects them. Among those who haven't started saving at all, 46% said the same.
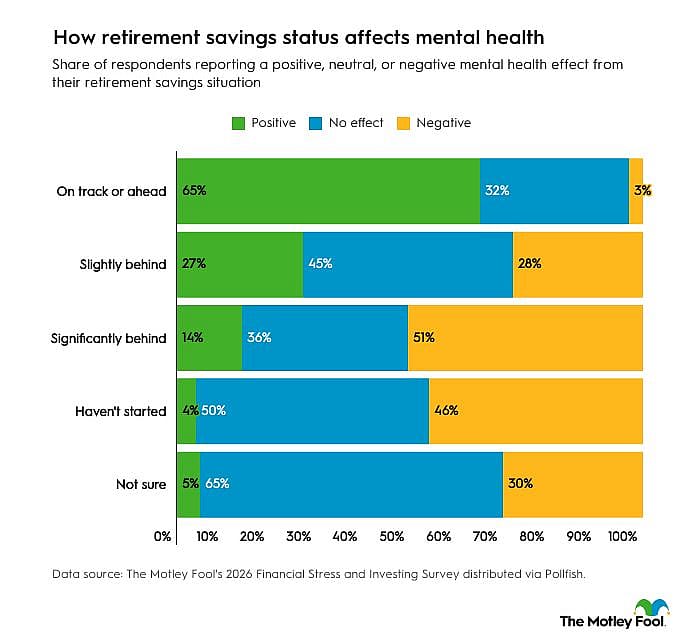
Avoidance is most prevalent among millennials. Among millennial respondents who said retirement savings negatively affect their mental health, 53% reported saving less or stopping entirely as a result, the highest rate of any generation in the survey. That can create a self-reinforcing cycle, where anxiety about a retirement savings shortfall makes the shortfall more likely to grow.
The Motley Fool's 2026 Financial Stress and Investing Survey shows financial stress around investing can impact every stage of the investing process: keeping some people out of markets, pushing others to panic-sell or over-monitor, and causing nearly half of retirement-stressed Americans to save less rather than more.
There are ways to limit the emotional side of investing, although feeling the rush of a portfolio achieving big returns, or the fear and anxiety when the market plunges, is natural.
Automating contributions to a diversified portfolio can eliminate hand-wringing over timing investments. Scheduling portfolio check-ins reduces emotional exposure to short-term market swings. Remembering that the stock market has a correction every one to two years, but has returned around 10% annually over nearly the last century, can provide important perspective on a downturn or choppy sessions.
Financial anxiety around investing is not just a mental health issue. It can act as a drag on long-term wealth growth by reinforcing patterns that make it harder to build wealth in the first place, compounding over time in the same way returns do. Recognizing that stress-driven responses to investing anxiety are common and that structural routines can reduce their impact is a first step toward investing with more consistency and less anxiety.
Does financial stress affect investing behavior?
According to the Motley Fool's 2026 Financial Stress and Investing Survey, 67% of active investors said financial stress or anxiety causes at least one behavior that can work against long-term investing goals, including avoiding investing, panic-selling, compulsive portfolio-checking, and delaying decisions.
Why do people make emotional investing decisions?
Fear and excitement are the two primary drivers: The Motley Fool's 2026 Financial Stress and Investing Survey found that 19% of respondents have sold investments out of fear of losing more money, and 17% have bought into something due to excitement or fear of missing out.
How does financial stress affect retirement savings?
Among Americans who said their retirement savings situation negatively affects their mental health, 48% reported that the resulting stress causes them to save less or stop saving altogether, according to the Motley Fool's 2026 Financial Stress and Investing Survey.
The Motley Fool's 2026 Financial Stress and Investing Survey was designed to measure how financial stress and anxiety affect investing behavior, including whether it keeps people out of the stock market, drives panic-selling or portfolio over-monitoring, and shapes retirement savings decisions.
The survey was conducted via Pollfish on April 21, 2026, and included 2,000 American adults ages 18 and older. To ensure results reflect the broader U.S. adult population rather than just people who seek out surveys, Pollfish reaches respondents through apps and websites they already use, rather than through opt-in survey panels, helping reduce self-selection bias. Results were weighted by age and gender to reflect the U.S. adult population, using U.S. Census Bureau benchmarks. The margin of error for the full sample is approximately plus-or-minus 2.2 percentage points at the 95% confidence level.
Generational definitions used: Gen Z (born 1997-2012, ages 18-29 at time of fielding), millennials (born 1981-1996, ages 30-45), Gen X (born 1965-980, ages 46-61), baby boomers (born 1946-1964, ages 62 and older).
This story was produced by The Motley Fool and reviewed and distributed by Stacker.